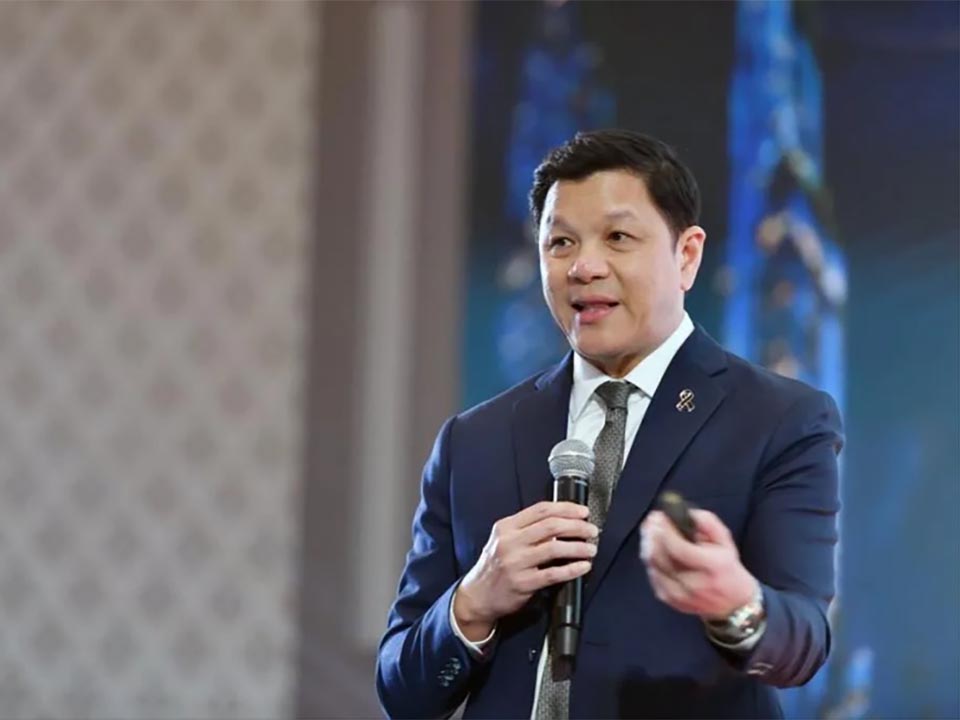
BANGKOK, Thailand – Thailand’s economy is expected to grow 2.3% in 2026, supported by strong exports and investment in artificial intelligence technology, despite flooding and longstanding structural weaknesses, Bank of Thailand Governor Vitai Ratanakorn said.
Vitai said the growth forecast was in line with estimates from several research institutions, which project expansion of 2.0–2.3%. Inflation is expected to reach around 2.2% this year, reflecting what he described as relative economic stability and resilience. “Despite ongoing problems, including flooding, the economy still has momentum,” Vitai said, adding that exports were performing well and Thailand could benefit from the global wave of AI investment.
Exports are forecast to grow by 17–18% in 2026, while private and foreign investment is expected to expand by around 13%, a strong performance compared with recent years. Investment in AI-related technology is expected to remain an important driver of growth, providing further opportunities for Thailand to attract capital and sustain economic momentum. However, Vitai warned that deep-rooted structural problems continued to constrain the country’s long-term growth potential.
Thailand’s economic growth has gradually declined from around 5% in earlier periods to approximately 2% in recent years, while its potential GDP growth rate has fallen to about 2.7%, he said. Among the key challenges are decades of insufficient investment, declining productivity and competitiveness, continued reliance on traditional industries, an ageing population and a shrinking workforce. Weaknesses in the education system and mounting public and household debt are also weighing on the economy. Household debt stands at around 86–87% of GDP, placing Thailand among the countries with the highest household debt ratios globally.
Vitai stressed that these structural weaknesses could not be resolved through a single government programme or policy measure. The central bank, beyond its responsibility for monetary policy, has expanded its role in supporting efforts to address structural problems, sustain economic activity and improve living standards, particularly for small and medium-sized enterprises (SMEs).
He called for coordinated action across government agencies and other sectors to improve productivity, strengthen businesses and put Thailand on a more sustainable growth path.
While strong exports and technology investment offer near-term support, Vitai’s assessment underscores the challenge of translating that momentum into stronger long-term economic growth.