BANGKOK, Thailand – Kasikornbank reported a net profit of 12.72 billion baht for the third quarter of 2026, down 2.1% year on year, as weaker financial investment income and lower fee revenue weighed on results. For the first nine months, however, net profit rose 3.43% to 40.635 billion baht, supported by growth in non-interest income.
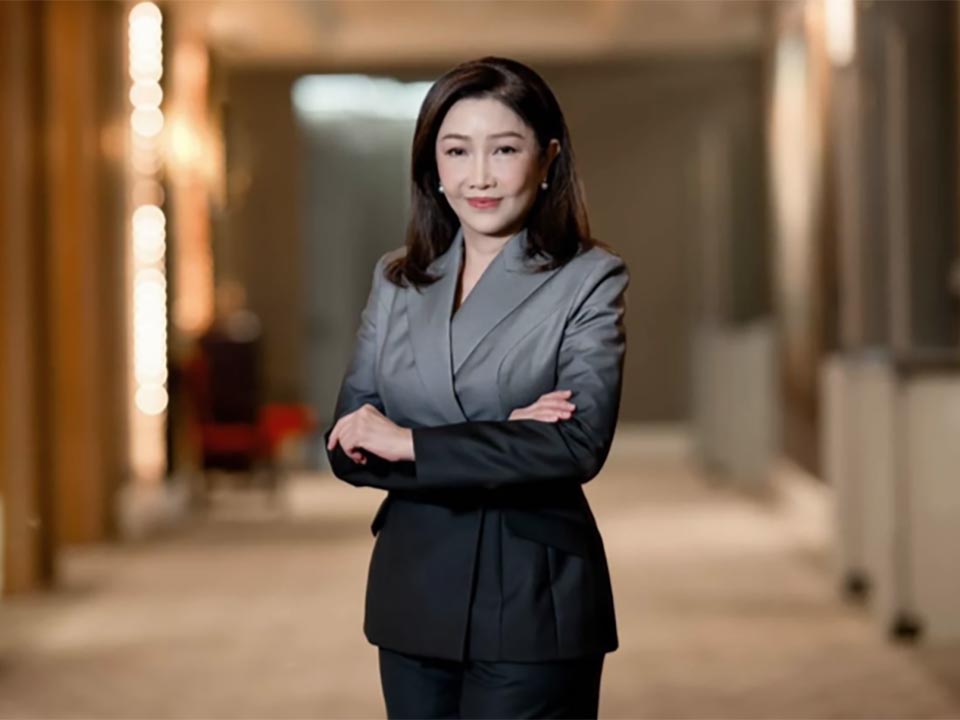
Chief Executive Officer Kattiya Indaravijaya said the bank and its subsidiaries recorded third-quarter net profit 527 million baht lower than in the previous quarter, a decline of 3.98%. Net fee and service income fell 5.29% quarter on quarter to 9.841 billion baht, reflecting market conditions and changes under new fee-collection standards.
Net interest income remained broadly stable from the previous quarter at 31.602 billion baht. Other operating expenses declined by 858 million baht, or 4.14%, to 19.892 billion baht, following continued efforts to improve operational productivity.
The bank set aside 10.329 billion baht for expected credit losses in the third quarter, an increase of 3.09% from the previous quarter. Its coverage ratio for non-performing loans rose to 177.90%, from 173.90% in the second quarter, to provide a buffer against economic uncertainty and domestic and international risks.
For the first nine months of 2026, net profit attributable to the bank reached 40.635 billion baht, an increase of 1.348 billion baht, or 3.43%, from the same period last year. Excluding a one-off gain of 1.455 billion baht from investment compensation, net profit would have been 39.311 billion baht, broadly in line with the previous year.
Net interest income for the nine-month period fell 8.87% to 94.992 billion baht, reflecting lower interest rates and reductions in lending rates intended to ease customers’ financing costs. Net interest margin stood at 2.89%. The decline was offset by non-interest income, which increased 21.51% to 51.894 billion baht. Growth came from wealth management, fund management, investment services and insurance offerings.
Other operating expenses fell 3.07% to 59.922 billion baht, while the cost-to-income ratio stood at 40.79%. The bank said it continued to improve productivity through workforce management, process improvements and the use of technology, including artificial intelligence. Operating expenses are expected to rise in the fourth quarter due to seasonal factors.
Expected credit-loss provisions for the first nine months totalled 30.171 billion baht. The average expected credit-loss ratio against loans stood at 1.60%, at the upper end of the bank’s 2026 target range of 1.40% to 1.60%.
Kattiya said Thailand’s economy received support from government stimulus measures during the third quarter, but the recovery remained uneven. Activity linked to the artificial intelligence cycle, particularly electronics exports and investment in digital and electronics industries, continued to drive growth. Tourism, however, had yet to recover fully, while households remained under pressure from high living costs and debt burdens.
Looking ahead to the final quarter, continued government measures to support consumption could provide some support to economic activity, but their overall impact may be limited by tighter budget constraints. Household purchasing power remains fragile and faces additional pressure from flooding, while uncertainty in the Middle East continues to keep global energy prices and other production costs elevated. (Story, Photo: Prachachat Business)